
Dollar and Fed should contain EM volatility
- Like nearly all assets, EM debt (except some currencies) is not cheap. However, for our asset class a downward trending US dollar has historically served to dampen asset price volatility.
- The Fed’s multi-year commitment to low interest rates will further reduce the probability of sharply lower moves in asset prices. Understandably, EMD markets are pricing in very low probabilities of default.
- In the absence of a catalyst that upsets the market narrative around these two factors we would broadly expect asset price movements to be within fairly narrow ranges, even as the likelihood of sharp moves higher is reduced by current price levels.
While a Fed pledge for a long period of low rates is a boon to asset prices, it also diminishes price volatility, since all of the implications for markets that derive from a new interest rate path are comfortably in the future. It is no different for emerging markets. But nearly as important for this asset class is the path of the US dollar.
Figure 1 shows a Schroders index that blends the level of credit default swap spreads for major EM countries. While major risk-off episodes increase default fears by this measure, so too does a rising dollar. The all-time low for this index occurred prior to the global financial crisis, but also in conjunction with the low in the dollar following a fall that began in 2002. Other broad movements like the rise from 2014 to 2016 and the rise from 2018-2019 also correlate with rises in the dollar.
Figure 1
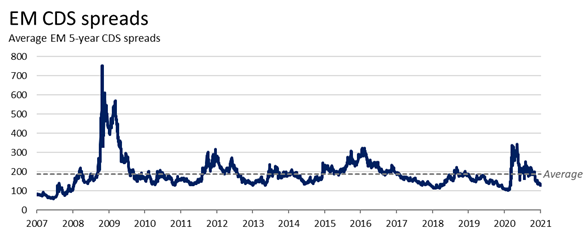
Source: Bloomberg, as of January 5, 2021. The chart measures a proprietary blend of 5-year credit default swap spreads for emerging countries (including: Brazil, Colombia, Hungary, Indonesia, Mexico, Russia, South Africa, and Turkey). This data is for the period of January 1, 2007 through January 5, 2021. Past performance is no guarantee of future results. Performance for other time periods would differ.
So, while we can recognize that prices are not cheap in EM and are outright rich for investment grade dollar debt, it’s also apparent that we lack a major catalyst for a large correction as long as the Fed is sidelined and the dollar is falling. We believe, a change in either of these conditions would require a change in the outlook for EM--which we are not yet seeing.
Subscribe to our Insights
Visit our preference center, where you can choose which Schroders Insights you would like to receive
The views and opinions contained herein are those of Schroders’ investment teams and/or Economics Group, and do not necessarily represent Schroder Investment Management North America Inc.’s house views. These views are subject to change. This information is intended to be for information purposes only and it is not intended as promotional material in any respect.
Topics